Familiarity Without Compromise: A Conflict-of-Interest Framework for Assessors in Small Sectors
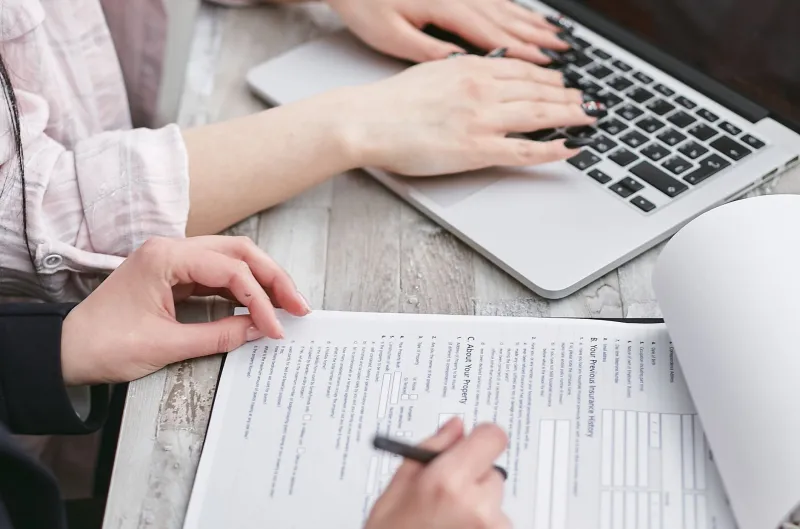
Photo: vocational assessor reviewing portfolio with colleague in small engineering workshop UK, via images.sftcdn.net
In sectors such as engineering, construction, adult care, hairdressing and logistics, the assessor pool is small and the professional network is smaller still. Assessors routinely encounter candidates they have trained, worked alongside, supervised or may soon employ. Familiarity is not misconduct. It is a foreseeable condition of assessing in a tight-knit industry, and it requires a deliberate response rather than an assumption that professional judgement will always remain untouched.
Why informal reassurance is not enough
Most assessors will say, honestly, that they can remain objective. The difficulty is that objectivity is hardest to detect from the inside. Familiarity can produce leniency towards a candidate whose work we have seen develop over years. It can also produce the opposite: an over-corrective harshness designed to prove that no favour has been shown. Both distort the assessment decision, and both are difficult to defend at appeal or during external quality assurance.
The risk is not limited to actual bias. It includes the perception of bias. A candidate who believes that a decision was influenced by a prior relationship may lose confidence in the process even where the judgement was sound. A documented framework protects the candidate, the assessor and the provider.
Stage one: declare at allocation, not at judgement
Conflict declarations should be collected before assessment activity begins, not after a difficult decision has been made. Providers should maintain a standing declaration at assessor onboarding and review it annually, alongside a short per-assessment declaration at the point of allocation.
Useful prompts include whether the assessor has trained or taught the candidate, line-managed them, worked alongside them in the past twenty-four months, has a family or close social connection, holds a financial interest in the candidate's employer, or has been involved in a previous dispute. The register should also capture less obvious connections: shared contracts, subcontracted work, or a candidate who is a former learner on a programme the assessor still delivers.
Declaration is not a confession. It is an allocation tool. The tone set by managers matters: assessors should be able to say that they know a candidate without fearing that the disclosure will be treated as an admission of weakness.
Stage two: triage the risk
Not every declared relationship requires recusal. A simple triage matrix helps distinguish manageable familiarity from a conflict that should remove the assessor from the decision. Consider proximity, recency, power and materiality.
Proximity concerns how close the relationship is. Recency concerns how recently it ended. Power concerns whether the assessor can affect the candidate's employment, pay or progression. Materiality concerns any financial or contractual interest. A final question is uniqueness: is there another competent assessor available?
A former colleague from three years ago with no current influence is different from a current line manager, a business partner or a close relative. Low-risk declarations can proceed with safeguards. Medium-risk declarations should require independent quality assurance. High-risk declarations should lead to recusal or reassignment. The decision should be recorded by a responsible officer, not left solely to the assessor concerned.
Stage three: protect the evidence
Familiarity influences not only the final judgement but also the evidence that reaches it. An assessor who knows a candidate may over-credit workplace products they recognise, or fail to probe claims because the context feels familiar. A useful safeguard is to agree the assessment plan and sampling frame before reviewing candidate-specific evidence. That reduces the scope for selective sampling.
At least one source of evidence should be produced or verified outside the assessor's direct influence. Witness testimony deserves particular care: an assessor should verify it directly with the witness rather than relying on a candidate's account of what a supervisor said. Where possible, avoid conducting assessment in a setting so familiar that challenge feels socially awkward.
Stage four: independent verification
Independent verification means more than a second signature on an already-formed decision. The independent assessor or internal quality assurer should review the raw evidence, the assessment rationale and the candidate's responses, and should have no material connection to the candidate or the assessor. Where the provider is small, an out-of-area IQA or a remote review by someone outside the local network may be the most practical route.
Verification should benchmark the candidate against the standard, not against last year's cohort or against the assessor's memory of the candidate's earlier work. Awarding organisations and end-point assessment organisations may have their own conflict rules; these should be read alongside the provider's internal framework, not replaced by it.
Stage five: escalation and recusal
Recusal should be treated as a quality action, not an admission of fault. The framework should state who makes the decision, how quickly reassignment is arranged, and how the candidate is informed. Communication should be neutral and should not imply wrongdoing by the candidate.
If a conflict is discovered late, the provider should consider whether the decision needs independent re-assessment. The record should explain what was discovered, what action was taken and why. Appeals procedures should acknowledge that conflict declarations exist and explain how they are reviewed.
Worked scenarios
A construction assessor discovers that a candidate was a former colleague on the same site eighteen months ago, and that the candidate's current supervisor is the assessor's brother-in-law. This is a high-risk declaration: the assessor should be replaced, or the decision should be subject to independent verification by someone with no connection to the site or the family.
An adult care assessor trained a candidate two years ago but has no current power over their employment. This may be medium risk. It can proceed with an independent second review of the evidence and direct verification of witness testimony.
A hairdressing assessor owns a salon that employs the candidate part-time. This is a direct financial interest and should lead to recusal. A logistics assessor is the only available assessor in the region and the candidate is a former colleague. Where recusal is impossible, the provider should document the constraint and apply stronger safeguards: remote IQA, independent witness verification and a larger evidence sample.
Documentation and culture
The record should be short and proportionate: the parties involved, the nature of the relationship, the risk rating, the safeguards applied, the decision-maker and the review date. Retain it in line with awarding organisation requirements and data protection obligations.
Conflict management also belongs in CPD. Annual scenario rehearsal, standardisation sessions and IQA calibration can help assessors practise the awkward conversation of declaring a relationship early. Managers should plan capacity so that recusal does not leave a gap that penalises the assessor who raised it.
Familiarity is not corruption. It is a predictable feature of small industries. A staged framework turns it into a managed risk, preserving the validity of the decision and the credibility of the assessor.